Europe's housing market is showing signs of life again, and this has been made possible because of cheaper mortgages.
A new report shows that home sales increased in 17 out of 20 European countries during 2025 as falling borrowing costs encouraged more people to buy homes.
Countries such as Belgium, Austria, France, and Spain all recorded stronger housing activity after interest rates eased, allowing buyers who had delayed their decisions to return to the market.
The trend highlights an important lesson for Kenya. And we could learn something or two.
While demand for homeownership remains high, the cost of financing continues to keep many buyers on the sidelines.
Mortgage rates in Kenya are often in the double digits, making monthly repayments unaffordable for many middle-income households.
The Kenya Mortgage Refinance Company (KMRC) has helped lower borrowing costs for qualifying homeowners, with mortgage rates of around 9% offered through participating lenders. However, these products remain limited compared to the wider mortgage market.
For example, that 9% rate is only available once, and as of now, it is mainly given to salaried individuals or if self employed, then your businesses needs to have its books in order and have some good cashflow.
That locks out a lot of people in the informal sector who might have the cash but do not have proper records to show their credit rating.
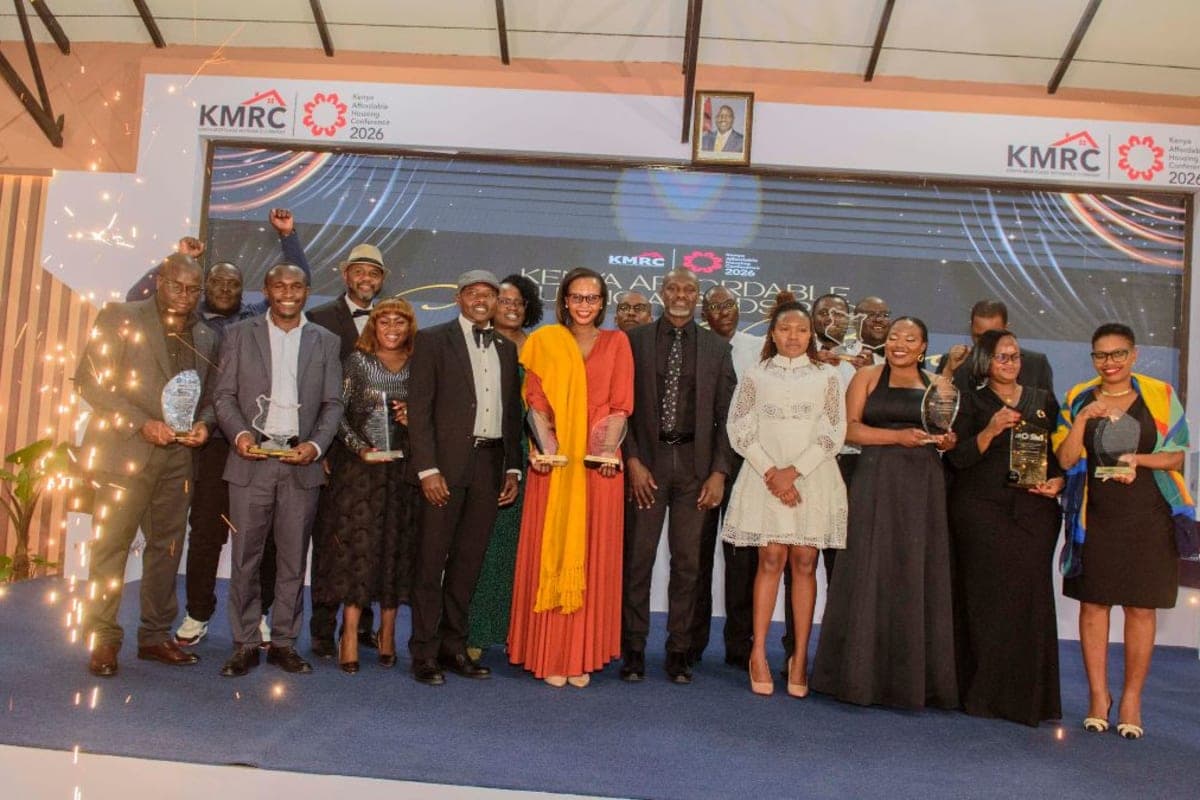
In an event I attended in 2026, however, KMRC stated they are working on a product for Kenyans in the informal sector. Let's wait and see if this will materialize.
Affordable financing does more than help individuals buy homes.
It stimulates construction, creates jobs, boosts consumer spending, and supports long-term economic growth.
Europe's experience suggests that when mortgages become more affordable, housing markets recover much faster.
For Kenya, making home financing cheaper and more accessible could be one of the most effective ways to unlock homeownership and accelerate growth in the real estate sector.